Selling & Money · 10 min read
How to Write a Simple Business Plan for a Small Nigerian Business
A practical guide to writing a one-to-two page business plan in Nigeria, with sections to include, a worked example, cash flow basics and how to use it.
By Noah Precious · Published 28 October 2026
Key takeaways
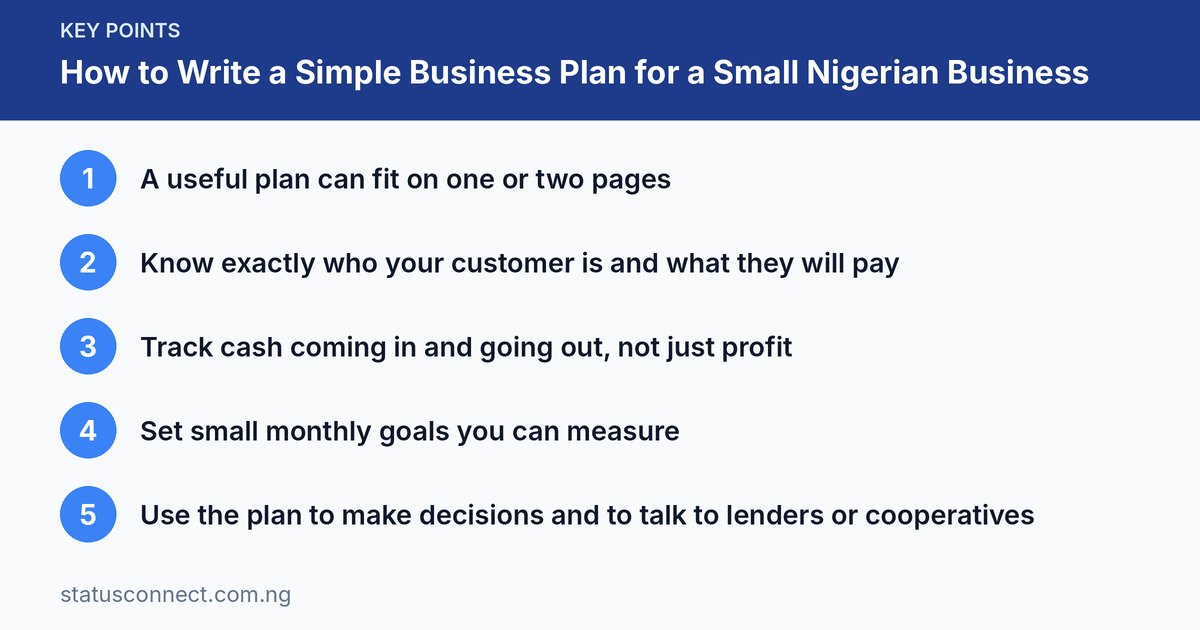
- A useful plan can fit on one or two pages
- Know exactly who your customer is and what they will pay
- Track cash coming in and going out, not just profit
- Set small monthly goals you can measure
- Use the plan to make decisions and to talk to lenders or cooperatives
Many small business owners in Nigeria hear "write a business plan" and picture a thick document full of charts that only banks understand. That is not what you need to start. A good small business plan is one or two pages that answer a handful of honest questions: who are you selling to, what are you selling, how much does it cost you, how much will you earn, and what will you do next month? If you can answer those on paper, you are already ahead of many people who start by buying stock and hoping for the best.
This guide shows you how to write that short plan, with a worked example for a food vendor, plain explanations of cash flow, and ideas for how to use the plan when you talk to a bank, a cooperative society or a grant programme.
Why a short plan is worth your time
A plan does three practical things.
- It forces you to do the maths before you spend. Writing down the cost of ingredients, transport, packaging and data shows you whether the business can actually make money.
- It helps you say no. When you have written your goal, it is easier to ignore distractions, like a new product line that does not fit your customers.
- It gives other people something to read. A cooperative officer, a mentor or a possible partner can understand your business in five minutes.
You do not need special software. A notebook, a phone notes app or a simple spreadsheet is enough. If you are still deciding what business to start, read our guide to starting a small business in Nigeria with low capital first and then come back here.
The sections your plan needs
Think of the plan as a template with seven short parts. Each part can be a few lines.
1. Business summary
Write two or three sentences: what you sell, where you operate, and who you serve. Example: "I sell home-cooked jollof rice and chicken lunch packs to office workers around Ikeja, Lagos, with delivery by bike on weekdays."
2. Customer
Describe your main customer in plain words. Age range, job, area, how they usually buy, and what they complain about. "Office workers who want a clean, quick lunch under a fixed budget and are tired of queuing" is far more useful than "everyone who likes food." The clearer this is, the easier it is to decide where to advertise and what to post.
3. Product and price
List your main products and what each one costs you to make. Then decide your selling price. Our article on how to price products on WhatsApp in Nigeria walks through cost, margin and common pricing mistakes, so you do not sell at a loss without noticing.
4. How you will reach customers
Write down two or three channels you will actually use, not ten you will forget. For many Nigerian sellers these are WhatsApp Status, referrals from existing customers, and one local community or market. If you are unsure, our guide on getting customers without ads has a list to choose from.
5. Costs and money
This is the heart of the plan. Split costs into two kinds:
- Start-up costs: things you buy once or rarely, such as a gas cooker, a freezer, sewing machine, or branded packaging.
- Running costs: things you pay repeatedly, such as ingredients, fuel or transport, data, rent share, helpers and platform fees.
Then estimate your monthly sales and subtract running costs to see what is left.
6. Goals for the next three months
Pick two or three goals with numbers you can check. For example, "reach 20 lunch orders a day," "have 15 repeat customers each week," or "save a set amount every month for a second cooker." Avoid vague goals like "grow big."
7. Risks and backup plan
List the three things most likely to hurt you and what you would do. Price changes in ingredients, a rider who does not show up, power cuts, or a slow month after festive seasons are common ones. A short backup plan, such as a second supplier or a smaller menu when prices jump, can save your month.
A worked example (illustrative numbers only)
The figures below are made up to show the method. Your real costs will be different, so replace each number with your own from receipts and market visits.
Imagine a small lunch-pack vendor. She plans to sell 20 packs a day, five days a week, so about 400 packs in a 20-day working month.
- Selling price per pack: 2,500 naira (example).
- Ingredient and packaging cost per pack: 1,400 naira (example).
- Money left per pack before other costs: 1,100 naira.
For 400 packs, that is 440,000 naira left in the month before other costs. Now she lists her other monthly costs, again as examples:
- Delivery and transport: 90,000 naira.
- Gas and cooking fuel: 40,000 naira.
- Data and phone: 10,000 naira.
- Helper's pay: 100,000 naira.
- Small repairs and miscellaneous: 20,000 naira.
Those total 260,000 naira. Subtracting from 440,000 leaves about 180,000 naira for the month. That is her estimated profit, and from it she must pay herself and set money aside. The exercise also shows her something important: if she sells only 10 packs a day, her margin shrinks quickly because transport and the helper's pay do not halve. Writing it down lets her see the break-even point instead of guessing.
A fashion seller would follow the same pattern: fabric, sewing cost or tailor's fee, accessories, packaging and delivery per item, then selling price, then monthly volume.
Cash flow in plain language
Profit and cash are not the same thing. Profit is what is left on paper after costs. Cash flow is the actual money moving in and out of your hands, and when. Many healthy businesses fail because they run out of cash at the wrong moment.
Here is a simple way to track it. Take one page for each month and make three columns: money in, money out, and balance at the end of the week. At the start, write what you have available. Each week, add customer payments and subtract what you spent.
Watch out for these common cash traps:
- Buying too much stock at once. Money sitting on a shelf cannot pay your rider.
- Giving goods on credit without a date. If a customer owes you, write the amount and the day they promised to pay.
- Mixing personal and business money. Pay yourself a fixed amount and keep the rest for the business. A separate account, even a simple one, makes tracking easier.
- Forgetting seasonal costs, like school fees, festive periods or rent renewals.
If you take payments through transfers on chat, read our guide on accepting payments safely when selling on WhatsApp so your records match what actually reached your account.
Setting goals you can measure
A good goal has a number and a date. Compare these two:
- Weak: "I want more customers."
- Strong: "By the end of January, I want 30 customers who have ordered at least twice."
Break the bigger goal into weekly checks. Every Sunday, spend ten minutes asking: how many orders did I get, how much did I spend, how much did I keep, and which customers came back? If the answer is worse than planned, change one thing next week, such as your posting time, your price or your menu, rather than changing everything at once.
Using your plan with banks, cooperatives and grants
A short plan can help when you ask for money, but be realistic. Lenders, cooperative societies and grant programmes each have their own forms, rules and requirements, and these change. Some may ask for a registered business, bank statements, a guarantor or a longer, formal document.
Here is how to prepare:
- Keep your records. Receipts, sales notes and bank statements show that the business is real.
- Consider registering. Many programmes prefer a registered business name. Our CAC registration guide explains the general process, and you can confirm current requirements on the Corporate Affairs Commission website.
- Ask what they need first. Call or visit and ask for the application form and any required documents before you spend time writing.
- Be specific about the money. Say exactly what you will buy with the loan or grant, how it increases sales, and how you will repay or report.
- Avoid anyone who asks you to pay a "processing fee" for a guaranteed grant. That is a common trick. Our guide to spotting WhatsApp scams in Nigeria explains the warning signs.
Rules, fees and programmes change from time to time, so always check with the official source before you apply.
A one-page template you can copy
Open your notes app and type these headings, then fill each with a few lines:
- Business name, location and what I sell.
- My main customer and what they want.
- Products, cost per item, selling price.
- How I will reach customers this quarter.
- Start-up costs and monthly running costs.
- Estimated monthly sales and expected profit.
- Three goals with numbers and dates.
- Top three risks and my backup plan.
Review the page at the end of every month and update the numbers.
Mistakes to avoid
- Guessing costs instead of checking receipts and current prices.
- Forgetting to pay yourself, which hides the real cost of the business.
- Setting a plan once and never looking at it again.
- Copying a plan from the internet that does not fit your market.
- Planning for perfect sales every day with no allowance for bad weeks.
Frequently asked questions
Do I need a business plan if I am just selling on WhatsApp?
Yes, a short one helps. Even a simple list of costs, prices and goals can stop you from losing money on orders that look busy but leave nothing after delivery and data costs.
How long should a small business plan be?
One or two pages is enough for most small sellers. Longer documents are usually requested by lenders for larger amounts, and they can ask you for their preferred format.
Will a plan guarantee that I get a loan or grant?
No. A plan helps you explain your business, but approval depends on the lender or programme's own rules, your records and their available funds.
How often should I update my plan?
Check your numbers weekly and revise the plan monthly or whenever your costs or prices change noticeably. A plan that is out of date can mislead you.
Final thoughts
A business plan is not a school assignment. It is a working page that tells you where your money goes and where you are heading. Start with the seven sections, use your real numbers, and improve it every month. If you want to meet other sellers, suppliers and customers while you grow, you can join the Status Connect community and build your network one contact at a time.